

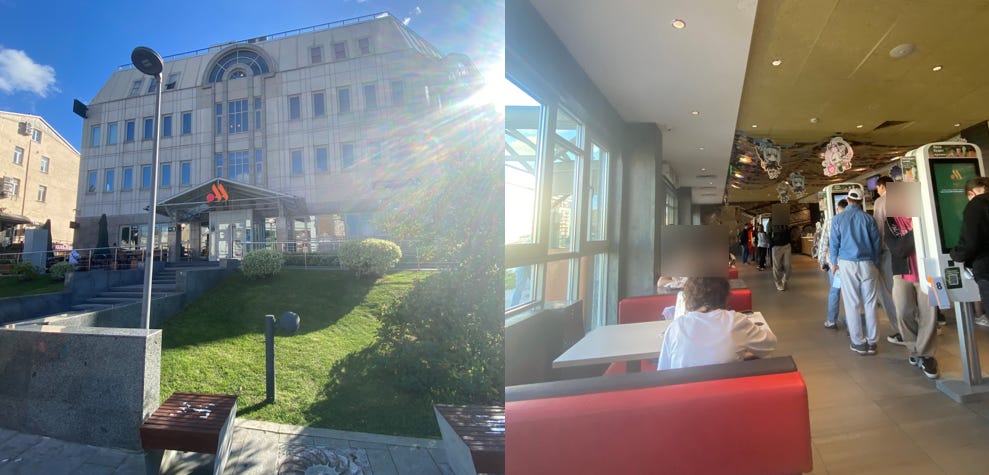
Moscow did not look like a capital under pressure this summer. The restaurants were full, prime real estate was transacting in cash, and the consumption boom was visible on the streets.
In Part 1, we looked at the top of the market, where titles are set and exits are priced. If commercial success carries that kind of title risk, Moscow ought to look poorer than it does. We go to the street to see where the condition is being absorbed and follow the discount through household savings, elite capital, advisory fees, and the cost of cross-border settlement.
What is paying for the spending
We read the spending boom less as structural wealth than as a function of constrained exit options. The composition of what is paying for it is far more interesting:
Wages, funded by the budget: RUB 16.84 trillion (~USD 199.2 billion), 38% of the planned 2026 federal budget, goes to defense and security, mostly on wages and supplier contracts. Unemployment sits at 2.3%, just above the 2.1% record low of August 2025, and the labor deficit is projected to exceed 3 million workers by 2030. The central bank notes that wages are still rising faster than productivity.
Household savings: Rosstat’s household savings share fell from 10% to 4.4% in H126, with deposit outflows in May and August 2026. Cash loan issuance rose 45% yoy in mid-2026, while unsecured consumer non-performing loans reached about 13% by early 2026.
The ruble: A 14% key rate and trade surpluses have kept the RUB near 81 to the dollar, which keeps imported goods within reach.
In several conversations, young Muscovites described a similar approach: hold six to nine months of runway and spend the rest, because tomorrow is not worth planning for. This is an illustrative sample, but the stories appear to match what the national accounts and delinquency data suggest.

Actual transaction prices for new-build flats in Moscow averaging about RUB 522,000 (~USD 6,200) per square meter within Moscow’s old boundaries in Q226, up 18% yoy. An average lot costs roughly RUB 28 million (~USD 330,000), about 20 years of Moscow’s gross median pay. With the policy rate at 14%, a market-rate mortgage is out of reach for most buyers. For this cohort, being priced out of housing appears to shift saving toward present consumption.
Two cash flows and no mortgages between them
A common assumption in Moscow is that prime new builds are being bought up by military personnel, or by people connected to the sector. The budget data paints a more precise picture.
In 2025-26, based on Janis Kluge’s (Russianomics) federal military budget tracking, regional sign-on bonuses escalated sharply, reaching an average of RUB 2.34 million (~USD 27,800) by late 2026. Individual bonuses reached RUB 4.1 million (~USD 48,800) in Khanty-Mansi, while Mari El, one of Russia’s poorest regions, pays RUB 2.5 million (~USD 29,600) including the federal portion. That money arrives as a lump sum, but even the Khanty-Mansi ceiling covers only about 15% of an average Moscow lot. It buys modest regional housing in cash.

The elite Moscow segment is an entirely separate capital pool. NF Group values elite new-build supply above RUB 1 trillion (~USD 11.9 billion) in H126, with weighted average prices reaching RUB 2.3 million (~USD 27,000) per square meter. According to BARNES, 70% of buyers cite capital preservation as their primary motive and up to 90% of transactions close without a bank mortgage.
That pool is small relative to the wealth that can absorb it. Russian billionaire wealth reached a record USD 696.5 billion across 155 people this year, the fourth straight year the headcount has risen. On the Credit Suisse/UBS Global Wealth Databook (2023) measure, the top 1% share held 56.4% of Russian wealth, the highest of any country measured at the time. Set against that pool, the entire RUB 1 trillion (~USD 11.9 billion) of elite inventory is small enough that a cohort this narrow could absorb it without difficulty. In an economy where domestic capital cannot easily move into convertible currencies, buying physical bricks for cash is a portfolio allocation decision as much as a property purchase.
Advisory fees under compression
The impact on high-earning professionals shows the same structural compression.
“There is plenty of domestic work available with state assets, PPP, subsidies, restructurings, but the fees are a fraction of what cross-border used to pay. A mandate that paid a million dollars now pays several hundred thousand.”
A view echoed in conversation among Moscow-based advisors
According to AK&M, M&A volume fell 24.6% to USD 41.12 billion across 399 deals in 2025, while state-controlled entities accounted for 40.8% of total deal value, the highest share on record. In H126, the market’s value rose 31.6% to USD 24.07 billion on 8.6% fewer transactions, and state-acquired assets made up 42.2% of that value.
Deal value is recovering, but the mix has changed. Cross-border advisory work has largely given way to domestic asset redistribution, where the counterparty is often the state. Domestic mandates come without a foreign counterparty or convertible-currency consideration, and they are priced accordingly.
An unwritten assumption
Most of the foreign money still reaching Russia now comes through trade rather than institutions. Parallel imports, which are legal under Russian law, move secondary stock at high volumes and thin margins through regional trade hubs. At the bottom of that supply chain we came across a small, foreign-owned importer and the colleague who runs its local sales.
The sales manager handles the firm’s entire Russian sales, inventory and customer relationships. When he asked for a performance payout, the owner refused, suggesting instead that he mark up goods himself, sell at a premium and keep the margin. Employed through a third-party agency rather than by the firm, he has no practical way to enforce the arrangement.
He has not launched his own distribution firm because he believes Russian law forbids foreign nationals from owning a business outright without citizenship. Russian corporate law permits 100% foreign ownership of a standard LLC. He is making operational decisions on the basis of a restriction Russian law does not impose.
Ask the two men separately what is wrong with doing business here and the complaint comes back pointed in opposite directions. The owner says customers do not pay, and has a buyer four months late on a bundle of goods who keeps promising to settle tomorrow. The sales manager says the firm ships late, the stock is not always what was sold, and product has gone to other buyers ahead of customers who pre-paid. Each is describing the other's half of the same problem. Neither has an enforceable contract in practice, and neither has anywhere practical to take it.
What follows describes how the discount is priced at each level of the market. At the top, value is capped, or perceived to be capped, through prosecutors, regional court orders and formal decrees. At the bottom, similar constraints operate without those mechanisms, through late or non-payment, delivery failures, misdescribed stock, widely held assumptions about the law and the absence of practical legal recourse. The pattern persists in part because many participants believe the rules are unfavorable to them.
The cost of settlement
For cross-border traders buying from China, the friction shows up at settlement. Routes run through third countries whose rules, and applicable export controls, change frequently. The two main channels reported by market participants:
Documented: Requires invoices, customs declarations and tax reporting at both ends. Institutional payment agents typically charge 5–8%, plus conversion and bank fees.
Undocumented: Matches counterparties holding RUB and RMB balances directly, outside documented trade flows.

Market participants report that spreads on these arrangements widen with ticket size. In 2023, comparable trades reportedly cost up to 40 bps. They are now reported at roughly 8–10x that.
Pricing a claim on a Russian cash flow
Part 1 asked what a claim on a Russian business is worth to the people who can still hold one. The listed market gives the cleanest answer.
The Moscow Exchange trades at under ~4x forward earnings, an earnings yield above 25%. A ruble deposit pays 12.9%. Add a conventional equity risk premium of around 5 points and a holder should need roughly 18% a year to own Russian equity rather than cash. The market is demanding about 7 points more than that before adjusting for expected earnings growth. Positive growth would widen the gap and negative growth would narrow it.
That excess is what investors charge for everything that sits between the earnings and the holder, i.e. capital controls, the tax regime, sanctions, and the conditional title traced in Part 1. Title is only part of it, and on our back-of-envelope numbers, the market is pricing Russian equity as if there were roughly a 7% annual hazard of total loss (a rough shorthand that assumes zero recovery and risk-neutral pricing). That is the market’s number, and the argument here is about what investors charge and why.
Private markets show the same discount from the other side. Non-public equity accounts for roughly RUB 4 trillion (~USD 47.6 billion), 24% of ЗПИФ (closed-end fund) net assets, at end-Q225 (latest available data), with managers targeting IRRs of 30–35%. With the policy rate between 16% and 21% from December 2023 through 2025, realized returns in a fund wrapper would plausibly be closer to 20% once illiquidity, concentration and jurisdiction risks are priced in. The 10–15 point gap between target and realized return reflects the same discount collected through the fund structure.
The discount shows up across the balance sheets traced here as well. Household consumption funded by savings that cannot easily be converted into foreign currency, advisory mandates repriced to several hundred thousand, and an undocumented settlement spread of 3–4%.
As noted in Part 1, the “Ин” accounts, which have been open since December 2025 with explicit sovereign guarantees against freezing, had drawn no investment by June 2026. That remains the clearest test of trust.
A ceasefire or a rate cut would help the cyclical picture, but on its own would be unlikely to change how investors price property rights. What would narrow the discount:
Active deployment of foreign capital inside “Ин” accounts;
Transparent return of state-acquired assets to private ownership at market value;
A managed liquidity mechanism for blocked Type C balances (ruble accounts holding non-residents funds subject to restrictions); and
A statute of limitations on privatization challenges without the anti-corruption carve-out.
Until then, a claim on Russian cash flows remains a conditional yield, and at today’s prices, the market is charging around 7 points a year for the condition.
Disclaimer: This research piece above is for informational, entertainment, educational, and/or study or research purposes only. The information contained herein or discussed does not, should not, and cannot be construed as or relied upon and, for all intents and purposes, does not constitute or provide professional financial, investment, or any other form of advice. This research does not and should not be construed as an offer to sell or the solicitation of an offer to buy any securities or any other financial instruments in any jurisdiction, including where such actions are illegal. This research is not intended for publication in jurisdictions where it would violate laws. The research does not consider individual investment objectives or financial positions and merely expresses the opinions of its authors. Any investment involves taking substantial risks, including (but not limited to) the complete loss of capital. Every investor has different strategies, risk tolerances, and time frames. You are advised to perform your own independent checks, research, or study, and you should consult a licensed professional before making any investment decisions. The assumptions and parameters discussed or used are not the only reasonable ones, and no guarantee is given for their accuracy, completeness, or reasonableness. No promise is made that any indicative performance return will be achieved. The research draws on public information and on conversations with market participants. Sources are anonymized, and some quotes are condensed or reflect views heard from several people. Views attributed to individuals are their own. This piece is an investment analysis and is not intended as political commentary. No representation or warranty is given for the reliability, completeness, timeliness, accuracy, or fitness of this research, nor is any responsibility or liability accepted for any loss or damage. The authors (Pyramids and Pagodas) shall in no event be held liable to any party for any direct, indirect, punitive, special, incidental, or consequential damages arising directly or indirectly from the use of any of this material.
Thanks for the coverage.
Why use deposits 12.9% yield if usually government bonds are used to compute the risk free rate? Yield on them (bonds) is around 16% https://smart-lab.ru/q/ofz/